

Accepting card payments isn’t just about inserting a card into a machine or entering card information in a secure checkout form. Instead, it involves an entire payment infrastructure, and the terminology can confuse non-technical people.
A merchant account, payment gateway, payment processor, and payment service provider each handle a different part of moving a customer’s payment from checkout to your business bank account.
This detailed guide covers two main infrastructure components: merchant account vs. payment gateways.
Merchant Account vs Payment Gateway: Quick Comparison
The easiest way to remember the difference is this: a payment gateway securely collects and transmits payment data, while a merchant account supports processing and settling card payment funds before the provider pays those funds to the business.
| Merchant Account | Payment Gateway | |
| Role | Holds and settles payment funds | Collects and transmits payment data |
| Customer-facing | Rarely | Often |
| Handles | Money | Data |
| Works online | Yes | Yes |
| Works in person | Yes | Yes |
What is a Merchant Account?
A merchant account is a specialized account relationship that lets a business accept card payments and receive settled funds. In a traditional payment setup, card transactions settle through the merchant account before the provider transfers the funds to the business’s bank account.
Modern payment service providers (PSPs) can provide this functionality behind the scenes, so a business may never open or manage a separate merchant account.
How does a Merchant Account Work?
- The customer’s card issuer approves or declines the transaction.
- The merchant or payment system captures the approved transaction.
- The processor and acquiring side of the payment system move the transaction through settlement.
- The merchant account receives the settled funds in a traditional setup.
- The payment provider transfers the funds to the business’s bank account according to its payout schedule.
What does Merchant Account Functionality Handle?
- Receiving and temporarily holding card payment funds
- Settlement with card networks and issuing banks
- Risk and underwriting checks tied to your business
- Chargeback and dispute handling
- Compliance with card network rules
Merchant Account vs. Business Bank Account
These two terms often get mixed up, and it’s worth separating them.
A merchant account exists specifically to process and temporarily hold card payment funds before settlement.
Your business bank account is your everyday operating account, where settled funds land and where you pay expenses and payroll.
With many modern providers, you never see a distinct merchant account at all. The function still runs in the background; it’s just built into the provider’s platform rather than shown to you as a separate account.
What is a Payment Gateway?
A payment gateway is the piece of infrastructure that securely captures a customer’s payment details at checkout, things like card number, expiration date, and CVC, and transmits that information onward for authorization. It works as the secure link between your checkout page and the rest of the payment system.
You should check out 👉 How to Choose the Right Payment Gateway for International Transactions
How does a Payment Gateway Work?
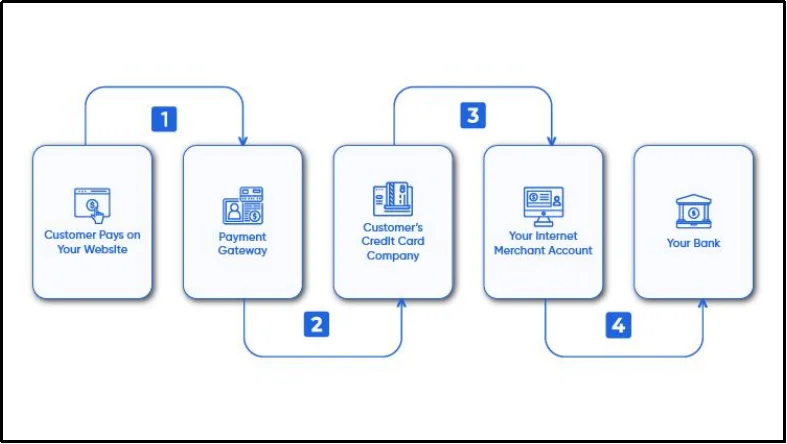
- The customer enters payment details at checkout or through a card terminal.
- The gateway encrypts and securely transmits that data.
- The gateway sends the transaction for authorization and relays the approval or decline back to the checkout experience.
What does a Payment Gateway Handle?
- Collecting payment information at checkout
- Encrypting and tokenizing sensitive card data
- Submitting the transaction for authorization
- Returning the authorization result to the merchant’s site or terminal
- Supporting the checkout or point-of-sale experience
Types of Payment Gateways
There are four primary types of payment gateways:
- Hosted gateways redirect customers to the provider’s secure checkout page. Minimal development work, though you get less control over checkout design.
- Integrated or self-hosted gateways embed payment fields directly into your website, giving you more control over the checkout experience but also more PCI DSS responsibility.
- API gateways give developers direct API access to build custom payment flows, common for apps, marketplaces, and platforms.
- Platform’s Payment solutions come built into an ecommerce platform or website builder, so most of the configuration is handled for you.
How Merchant Accounts and Payment Gateways Work Together
Although a merchant account and payment gateway serve different purposes, they work together to complete card payments. The gateway securely transmits payment information, while the merchant account enables the business to receive and settle the funds.
Step-by-Step Payment Backend Procedure:
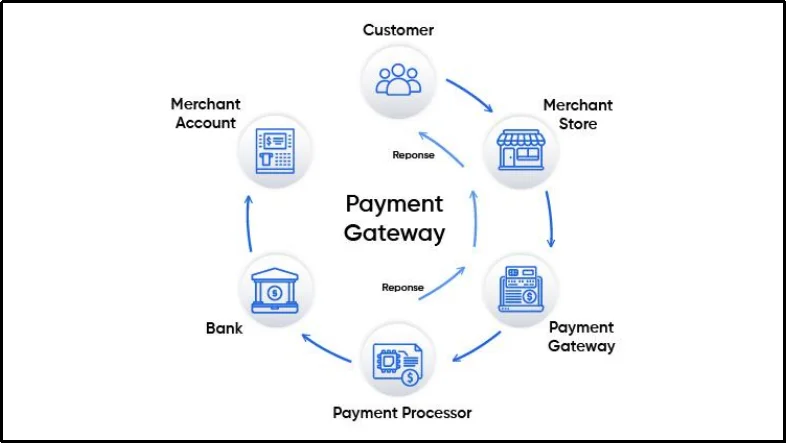
Step 1: Customer enters payment details at checkout or a card terminal.
Step 2: The gateway secures the payment data and forwards it.
Step 3: The processor routes the transaction to the relevant card network.
Step 4: The card network passes the request to the customer’s issuing bank.
Step 5: The issuing bank approves or declines the transaction.
Step 6: The authorization response travels back through the payment infrastructure to the gateway and checkout.
Step 7: The payment gets captured, meaning the merchant or their system confirms it wants to complete the approved transaction.
Step 8: Funds move through settlement, batched together with other transactions.
Step 9: Merchant account functionality receives the funds.
Step 10: The provider pays out the settled funds to the business bank account.
Authorization vs Capture vs Settlement vs Payout
Authorization: The issuer checks the card and available funds or credit, then approves or declines the transaction, typically in real time.
Capture: The merchant, or their system, confirms it wants to collect the authorized funds. This can happen right away or be delayed, depending on the business.
Settlement: Approved and captured transactions get batched and moved through the card networks and banks, turning the authorization into an actual transfer of funds.
Payout: The provider deposits the settled funds, minus fees, into the merchant’s business bank account, on a schedule that varies by provider, often next day or within a couple of business days.
Do You Need Both a Merchant Account and Payment Gateway?
Most businesses need both functions to accept card payments. What varies is whether one provider offers both functions or you use multiple providers.
Traditional setup: Merchant works with a dedicated merchant account provider (often through an acquiring bank), a separate payment gateway, and a processor, sometimes from different companies.
Modern PSP setup: Merchant works with a single payment service provider that bundles the gateway, processing, and merchant account functionality into one platform.
Plenty of businesses today never sign up for a standalone merchant account. The function still exists; it just runs behind the scenes as part of a PSP instead of being assembled piece by piece.
Common Merchant Account Structures and Categories
Merchant accounts generally fall into a few common categories based on how the account is structured and how payment processing is handled. Here are the common categories to know:
Dedicated Merchant Accounts
Dedicated merchant accounts are set up specifically for one business, usually through an acquiring bank or dedicated merchant services provider. Setup takes longer and involves underwriting, but businesses often get more customization and negotiated pricing at higher volumes.
Aggregated Merchant Accounts
Aggregated or shared merchant accounts come from a PSP, where many merchants’ transactions run through the PSP’s own merchant and acquiring relationship. Setup is fast and simple, with less individual customization and somewhat more exposure to account holds if the PSP flags unusual activity.
High-risk Merchant Accounts
High-risk merchant accounts serve industries with higher chargeback or regulatory scrutiny, such as subscription services, certain supplement brands, or travel businesses. These accounts usually come with higher fees or reserves, allowing these business types to accept card payments.
How Much Do Merchant Accounts and Payment Gateways Cost?
Pricing for merchant accounts and payment gateways rarely comes down to one number. Most providers charge across a handful of categories, and understanding each piece makes it much easier to compare offers or predict your actual monthly cost.
Here’s a list of categories that make up the total cost:
- Transaction fees, a percentage and often a flat fee per transaction
- Interchange fees, set by card networks and paid to the issuing bank, often passed through directly on interchange-plus pricing.
- Assessment or network fees, charged by the card networks themselves
- Gateway fees, if your gateway is billed separately from processing
- Monthly or platform fees, flat recurring charges
- Setup fees, one-time onboarding costs, more common with dedicated merchant accounts
- Chargeback fees, charged per dispute
- Currency conversion fees, relevant for international transactions
- Payout fees, occasionally charged for faster or international payouts
- Minimum monthly commitments, required by some providers
Why Total Processing Cost Matters
Two providers can advertise similar headline transaction rates and still land very differently once monthly fees, chargeback fees, currency conversion, and payout timing come into the picture. When comparing providers, estimate total monthly cost based on your actual transaction volume, not rates alone.
Merchant Account vs Payment Gateway: Detailed Comparison
Merchant accounts and payment gateways are often mentioned together, but choosing the right payment setup requires looking beyond their basic definitions. The comparison below focuses on the factors that matter when evaluating your options, including flexibility, integrations, and business needs.
| Factor | Merchant Account | Payment Gateway |
| Primary purpose | Supports receipt and settlement of card funds | Securely collects and transmits payment information |
| Main role | Handles payment funds | Handles payment data |
| Customer-facing | Rarely | Often |
| Handles card details | Depends on payment architecture | Often handles or transmits payment data |
| Handles settlement | Yes | Limited |
| Works with a processor | Yes | Yes |
| Works with ecommerce | Yes | Yes |
| Works in person | Yes | Can support POS and terminals |
| Setup | May involve underwriting | Usually integration and configuration |
| Fees | Depends on the provider or acquirer | Depends on the provider |
| Can be bundled by a PSP | Yes | Yes |
The right payment setup depends on your business model, transaction volume, technical requirements, and how much control you need over payment processing. A dedicated merchant account can provide more control over processing arrangements, while a payment gateway focuses on securely connecting your checkout or payment terminal to the payment-processing infrastructure.
Modern payment service providers (PSPs) can combine these functions, giving businesses a simpler way to accept and manage card payments.
What Is a Payment Service Provider?
A PSP is a company that bundles several payment functions, typically the gateway, processing, and merchant account or acquiring functionality, into a single service. That lets a business start accepting payments without separately sourcing and integrating each piece.
How PSPs Simplify Payment Processing
Businesses often use payment service providers because they speed up and simplify payment processes. PSPs offer:
- Faster onboarding, often same-day or within a few days
- One dashboard, one contract, one support relationship
- Simpler integration for developers
- A lower barrier to entry for small or new businesses
PSP vs Merchant Account
Many PSPs use an aggregated or payment-facilitator model instead of giving every merchant a traditional dedicated merchant account. This can simplify onboarding, although the exact account structure depends on the provider and market. That can mean less room to negotiate individually, in exchange for a much faster setup.
PSP vs Payment Gateway
A payment gateway is only one piece of what a PSP offers. A PSP usually includes a payment gateway, plus processing and settlement functionality, so the terms describe different scopes even though people often use them interchangeably.
Separate Providers vs All-in-One Payment Platforms
There are two common ways to build a payment setup: work with separate providers for different functions or use an all-in-one platform that handles most of the payment process.
Separate Payment Infrastructure
This route can offer more customization, negotiated pricing at scale, and more control over checkout and settlement setup, plus the flexibility to swap out individual pieces. The tradeoff is more integrations to manage, multiple contracts and support relationships, more technical complexity, and a longer setup time.
All-in-one PSP
This route usually means faster setup, simpler integration, a single dashboard and support line, and a lower barrier to entry. The tradeoff is less customization, pricing that may become less competitive at high volume, and greater dependence on one provider.
Which Approach is Better?
As a rough guide, newer or smaller businesses, and anyone who wants to launch quickly, tend to do well with an all-in-one PSP. Larger businesses with high, predictable transaction volume, or specific technical and compliance needs, are more likely to benefit from negotiating separate, dedicated components.
What to Look for in a Payment Provider
When considering a reliable payment provider, you should check the payment methods and currencies it supports, how quickly it settles funds, the security and fraud tools it provides, and how well it integrates with your existing systems. If you find a provider that meets these needs, you can scale your business without having to switch payment providers.
- Supported payment methods, such as cards, wallets, and bank transfers
- Supported currencies and countries
- Transparent transaction pricing
- Settlement and payout speed
- Recurring billing support
- Fraud detection and prevention tools
- Chargeback and dispute management
- PCI DSS support and compliance tools
- Integrations with your website, ecommerce, or POS platform
- API flexibility for custom development
- Reporting and analytics
- Customer support quality
- Ability to scale with your transaction volume
Common Merchant Account and Payment Gateway Misconceptions
There are a few misconceptions you should know. This may be what is stopping you from making the right choice.
- Merchant account = bank account: A merchant account temporarily holds card funds before they settle into your business bank account.
- Gateway = payment processor: A gateway transmits payment data, while the processor routes transactions and facilitates authorization.
- You always need a separate merchant account: Many modern PSPs bundle merchant account functionality into their platforms.
- Gateway = online payments only: Depending on the provider, gateways can also support in-person and card-present payments.
- The lowest transaction rate is always cheapest: Compare total costs, including monthly, chargeback, and currency fees.
How WP Easy Pay Fits Into WordPress Payment Processing
WP Easy Pay is a WordPress payment forms plugin that integrates with Square to help businesses accept payments directly through their WordPress site. It sits on top of the payment infrastructure so you can build payment forms, subscriptions, and invoices without wiring up each payment component yourself.
In practice, the flow looks like this: a customer fills out a payment form built with WP Easy Pay on your WordPress website, and Square’s payment gateway and merchant account infrastructure process and settle the transaction.
If you’re already using Square, or planning to, WP Easy Pay lets you build custom payment forms, multi-step forms, and subscription flows natively in WordPress, with reporting available inside your dashboard.
If you’re looking for a simpler way to accept payments without adding unnecessary complexity, WP Easy Pay can help. Get started today!
Frequently Asked Questions
What is the difference between a merchant account and a payment gateway?
A merchant account supports receiving and settling card payment funds, while a payment gateway securely collects and transmits the payment information used to process the transaction.
Do I need both a merchant account and a payment gateway?
Most businesses need both functions to accept card payments, though they often come from a single provider rather than two separate ones.
Is a payment processor the same as a payment gateway?
They’re related but different. The gateway collects and transmits payment data, and the processor routes that data between the gateway, card networks, and issuing banks to facilitate authorization.
Can I accept payments without a traditional merchant account?
Yes. Many PSPs provide merchant account functionality through their own aggregated or shared account infrastructure, so you often don’t need a standalone merchant account.
Is a merchant account a bank account?
It’s a specialized function for processing and temporarily holding card funds before they settle into your actual business bank account.
Does a PSP provide a merchant account?
Most PSPs provide merchant account functionality, typically through a shared or aggregated arrangement rather than a fully dedicated account.
What’s the difference between a PSP and a merchant account?
A merchant account is one component of card processing. A PSP bundles a merchant account’s functionality with a gateway and processor into one service.
Which is cheaper, a dedicated merchant account or a PSP?
It depends on transaction volume. PSPs often have simpler, flat pricing that suits smaller businesses, while dedicated merchant accounts can offer better negotiated rates at higher volumes.