

Businesses today can choose from traditional banking-based payment systems or modern FinTech payment platforms. While traditional payment methods continue to dominate many industries, FinTech companies have transformed payment processing with real-time transactions, digital wallets, automation, and developer-friendly integrations.
The challenge is knowing which option best fits your business. Factors such as transaction costs, settlement speed, security, customer preferences, and scalability all influence the decision.
In this guide, we’ll compare traditional vs FinTech payments, explain how each payment model works, examine their advantages and disadvantages, and help you determine the right payment solution for your business in 2026.
Why FinTech Payments Continue to Grow
Consumer payment behavior continues to shift toward digital-first experiences. Mobile wallets, contactless payments, subscription billing, and embedded finance solutions have accelerated the adoption of FinTech payment platforms across eCommerce, SaaS, retail, and service industries.
At the same time, traditional banking infrastructure remains essential for settlement, regulatory compliance, and large-scale financial operations. As a result, many businesses now combine traditional banking services with FinTech payment technologies to create a flexible payment ecosystem.
How to Choose Between Traditional and FinTech Payments
Choosing between traditional and FinTech payments can be challenging because both offer unique advantages. Traditional payment systems provide stability, regulatory oversight, and established banking relationships, while FinTech platforms focus on speed, automation, and digital-first experiences.
The right choice depends on factors such as transaction costs, settlement speed, customer preferences, compliance requirements, and business growth plans. To help you make an informed decision, we’ll first explain how each payment model works and then compare their key differences later in this guide.
What are Traditional Payments?
Traditional payments are transactions processed through established financial institutions, such as banks and card networks. These payment methods rely on conventional banking infrastructure to facilitate money transfers and are widely used for everyday consumer and business transactions.
Common examples include bank transfers, debit and credit card payments, checks, wire transfers, and cash deposits. Traditional payment systems are highly regulated and are often preferred for their stability, trust, and broad acceptance.
How Do Traditional Payments Work?
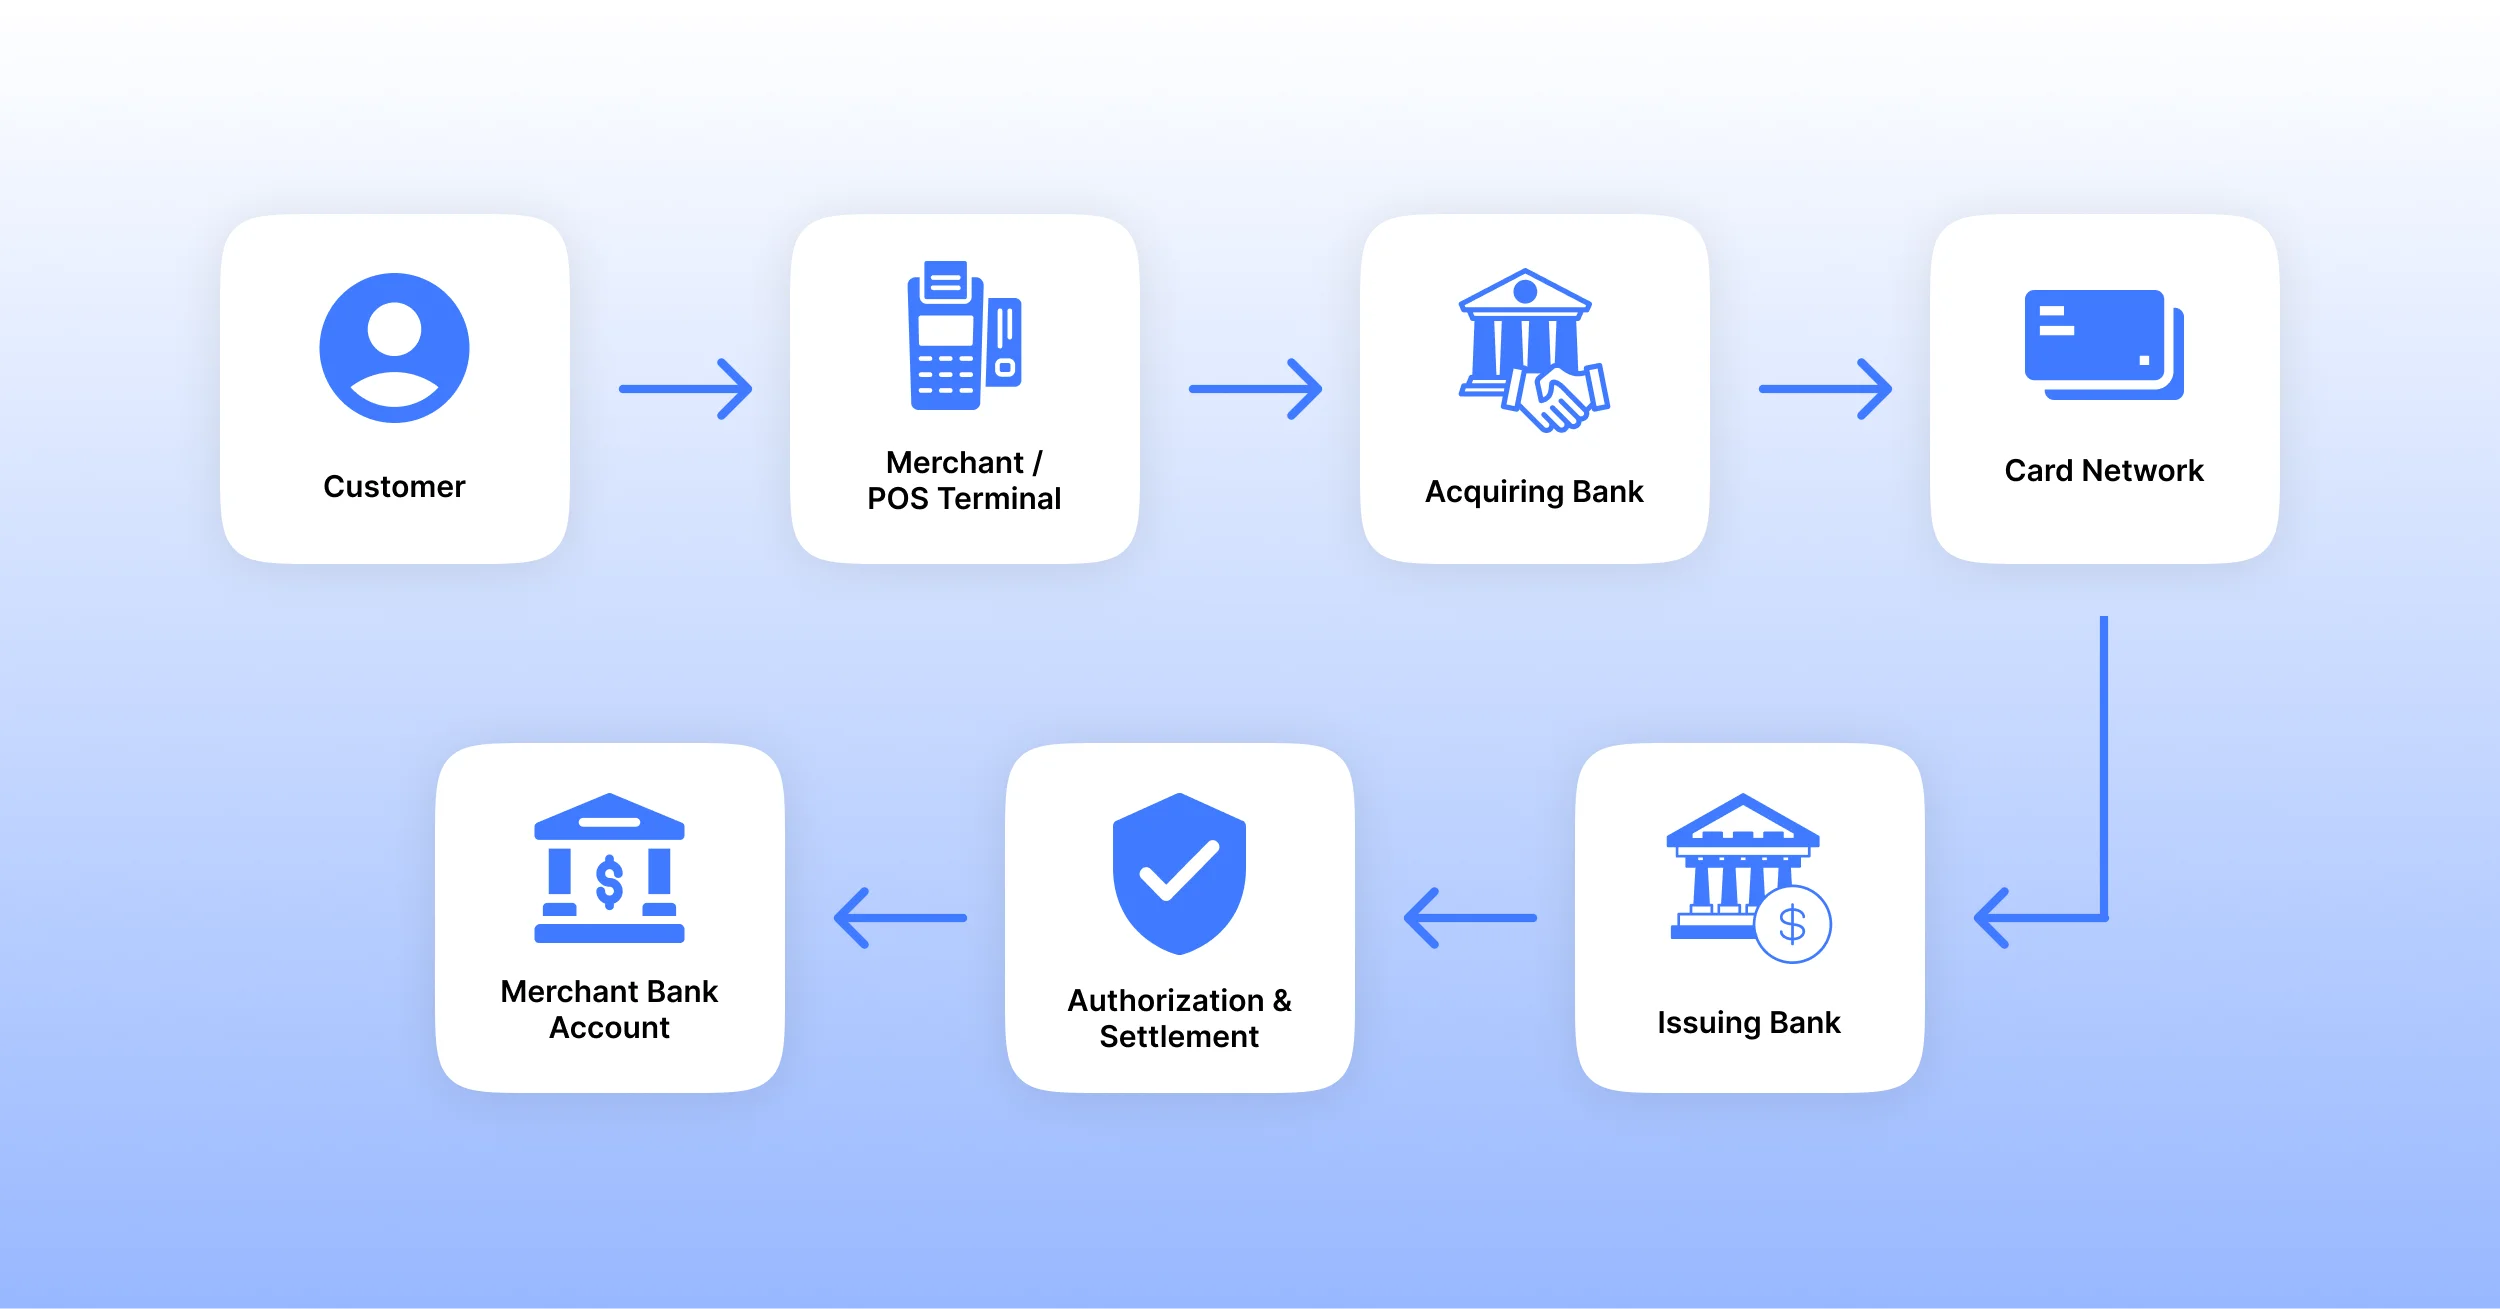
Customer
↓
Merchant / POS Terminal
↓
Acquiring Bank
↓
Card Network (e.g., Visa/Mastercard)
↓
Issuing Bank
↓
Authorization & Settlement
↓
Merchant Bank Account
)
Traditional payments follow a structured process involving banks and payment networks. When a customer initiates a payment, the transaction is routed through the relevant payment network for authorization by the customer’s bank or card issuer.
Once the issuing bank authorizes the transaction, the card network facilitates clearing and settlement between the issuing bank and acquiring bank. The acquiring bank then deposits the funds into the merchant account according to the agreed settlement schedule. Depending on the payment method and participating financial institutions, settlement may take anywhere from one to several business days.
What Is FinTech?
FinTech (Financial Technology) refers to technology-driven financial services that improve how consumers and businesses manage, transfer, borrow, invest, and receive money. FinTech companies use cloud computing, APIs, artificial intelligence, mobile applications, and automation to deliver faster and more accessible financial services than traditional banking systems.
Payment processing is one of the largest segments of the FinTech industry, powering digital wallets, payment gateways, Buy Now, Pay Later (BNPL) services, and embedded finance solutions.
What are FinTech Payments?
FinTech payments are digital payment solutions that use financial technology to help businesses and consumers send, receive, process, and manage money quickly and securely. Unlike traditional banking methods, FinTech payments use modern technologies to simplify payment processing, improve user experiences, and accelerate transaction authorization and settlement.
Common examples include digital wallets, payment gateways, payment processors, Buy Now, Pay Later (BNPL) services, embedded finance platforms, and real-time payment networks.
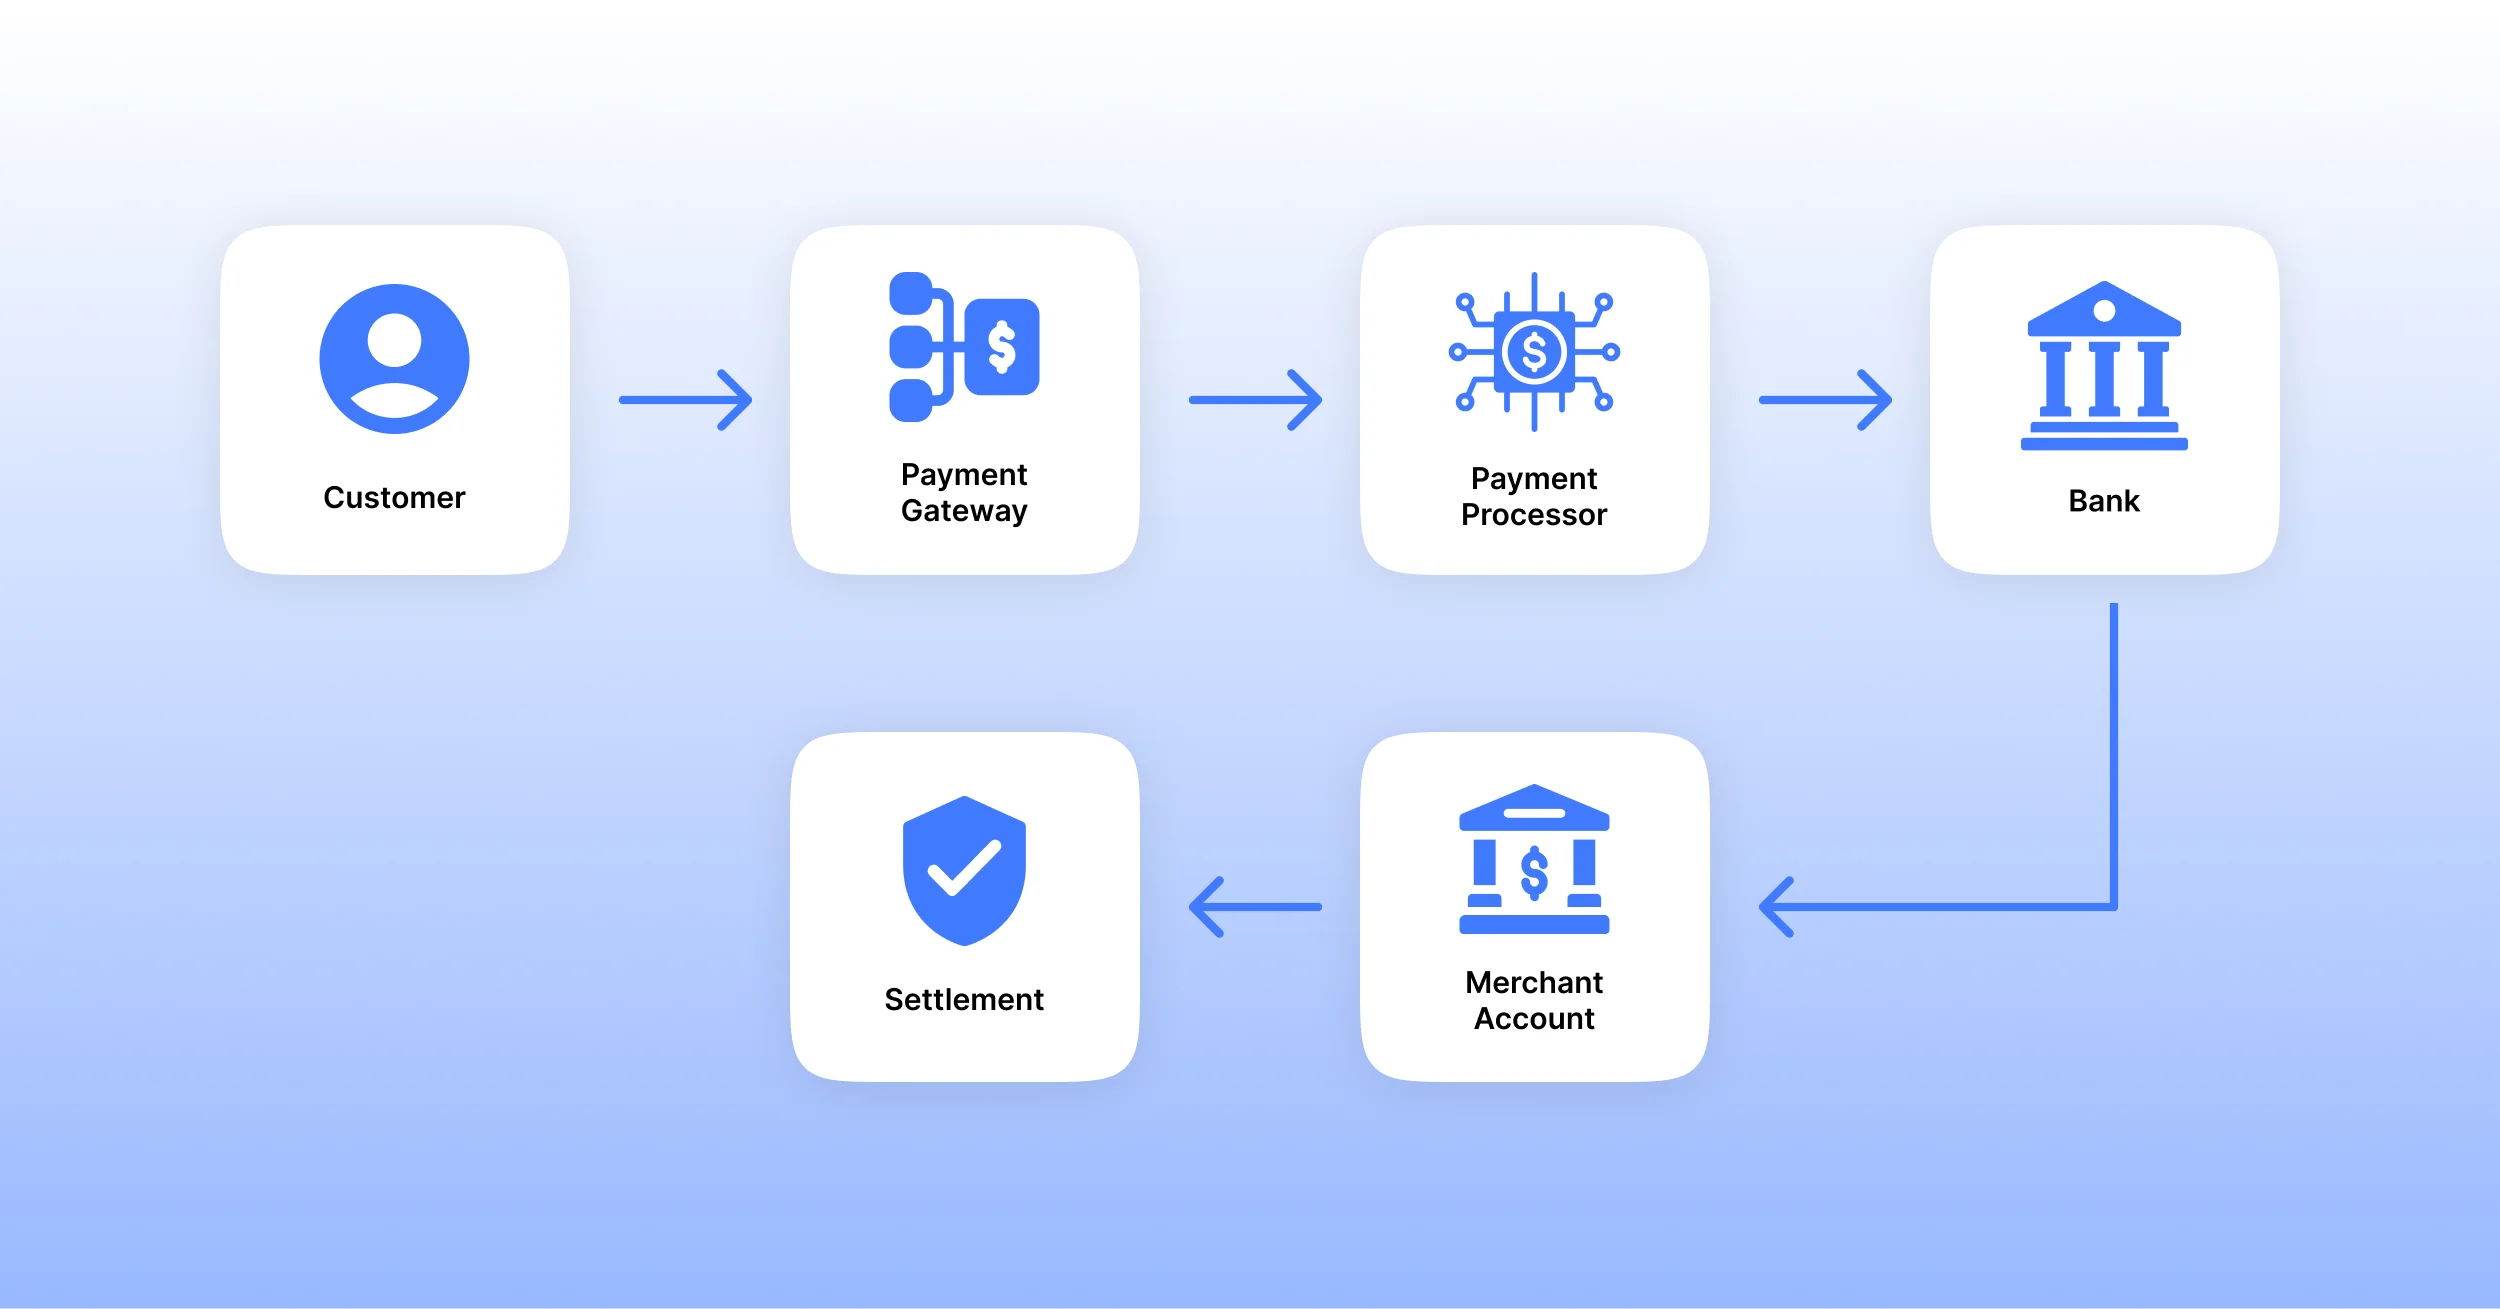
How Do FinTech Payments Work?
)
Customer
↓
Payment Gateway
↓
Payment Processor
↓
Bank
↓
Merchant Account
↓
Settlement
)
A typical FinTech payment follows an API-driven workflow that securely transmits payment data between the customer, payment gateway, processor, acquiring bank, and issuing bank. Modern FinTech platforms often use tokenization, encryption, fraud monitoring, and automated risk assessment to approve and settle transactions quickly.
Once the payment is approved, the acquiring bank or payment provider initiates settlement and transfers the funds to the merchant account according to the provider’s payout schedule.
Differences Between Traditional vs FinTech Payments
The table below compares their key differences to help you choose the option that best fits your business needs.
| Factor | Traditional Payments | FinTech Payments |
| Provider | Banks and established financial institutions | FinTech companies and digital payment providers |
| Transaction Speed | Typically 1–3 business days for settlement | Often real-time or same-day settlement |
| Pricing | May include setup, monthly, and transaction fees | Usually transparent, pay-as-you-go pricing |
| Integration | Limited APIs and longer implementation | Easy API integrations and developer-friendly tools |
| Security | Bank-grade security with regulatory oversight | PCI DSS compliance, encryption, tokenization, and AI-powered fraud detection |
| Scalability | Better suited for established organizations | Designed to scale quickly with growing businesses |
| Best For | Large enterprises, regulated industries, and traditional businesses | Startups, SMEs, eCommerce, SaaS, and digital-first businesses |
| Setup Time | Days to weeks | Minutes to days |
| Global Reach | Depends on banking network | Often supports international payments |
| Innovation | Slower feature adoption | Rapid innovation cycles |
| Automation | Limited | Extensive automation |
| User Experience | Conventional | Mobile-first and digital-first |
| Real-Time Payments | Limited | Commonly supported |
Both traditional and FinTech payment providers must comply with industry regulations and security standards. Depending on the region and payment type, businesses may encounter requirements related to PCI DSS, PSD2, Know Your Customer (KYC), Anti-Money Laundering (AML), and data protection laws.
Pros and Cons of Traditional vs FinTech Payments
| Traditional Payments | FinTech Payments | |
| Pros | – High customer trust– Strong regulatory oversight– Stable financial infrastructure– Wide acceptance across industries | – Faster setup and onboarding– Lower upfront costs– Modern integrations and automation– Flexible and scalable for growing businesses |
| Cons | – Slower onboarding and approval processes– Higher fees in some cases- Less flexibility and innovation- Manual paperwork may slow onboarding.- Legacy systems often require complex integrations.- Limited flexibility for digital-first business models. | – Features vary by provider– May depend on partner banks for some services- Regulatory coverage differs across regions- Service availability varies by region.- Some providers impose payout limits or account reviews.- Businesses may depend on third-party infrastructure providers. |
Popular FinTech Payment Methods and Examples
FinTech has introduced a wide range of digital payment methods that prioritize speed, convenience, and seamless user experiences. These solutions are widely used in eCommerce, mobile apps, subscription services, and digital businesses.
- Invisible Payment
Invisible payments complete transactions automatically without requiring customers to present cash or a payment card at checkout. Once a payment method is authorized, purchases are processed in the background, creating a seamless user experience. Common examples include ride-sharing apps, subscription services, and cashierless retail stores.
- Digital Wallet (eWallet)
Digital wallets securely store payment information, allowing users to make purchases using smartphones, tablets, or computers. They eliminate the need to carry physical cards while enabling fast and contactless payments. Popular examples include Apple Pay, Google Pay, Samsung Wallet, and PayPal Wallet.
- P2P (Peer to Peer) transfer
Peer-to-peer (P2P) payment services enable individuals to transfer money directly to one another through digital platforms. These services are commonly used for splitting bills, sending personal payments, or making small business transactions. They provide a convenient alternative to traditional bank transfers for everyday payments.
- Tokenized Card Payment
Tokenized card payments replace sensitive card details with a unique digital token during payment processing. This prevents merchants from storing actual card information, reducing the risk of fraud and data breaches. Tokenization also supports PCI DSS compliance while improving payment security.
- Wearables
Wearable payments allow users to make contactless purchases using smart devices such as smartwatches and fitness trackers. These devices securely store payment credentials and work similarly to contactless debit or credit cards. Popular options include Apple Watch, Garmin, and Fitbit devices with NFC payment capabilities.
- Mobile Payments
Mobile payments enable users to send or receive money and make purchases directly through a smartphone or tablet. They often use dedicated payment apps or built-in mobile wallet features for quick and secure transactions. Mobile payments are widely adopted for both online shopping and in-store purchases.
Businesses using WordPress can integrate modern FinTech payment solutions through plugins such as WP EasyPay. The plugin enables businesses to accept Square payments, digital wallets, and online card payments while simplifying payment processing and checkout management.
- Buy Now, Pay Later (BNPL)
BNPL services allow customers to split purchases into multiple installments while merchants receive payment upfront. Popular BNPL providers have become common in eCommerce because they increase conversion rates and average order values.
- Embedded Payments
Embedded payments integrate payment functionality directly into software platforms, marketplaces, and mobile applications. Users can complete transactions without leaving the platform.
Popular Traditional Payment Methods
Traditional payment methods continue to play a vital role in both consumer and business transactions. They are supported by established banking infrastructure and remain widely accepted across industries.
- Credit – Debit Cards
Credit and debit cards remain among the most widely accepted payment methods for both online and in-store transactions. They are processed through established banking networks and offer secure, convenient payment experiences. Most businesses accept card payments due to their global popularity and customer familiarity.
- Bank Transfers
Bank transfers move funds directly between bank accounts through secure banking networks. They are commonly used for business payments, payroll, invoices, and high-value transactions. While highly reliable, settlement times can vary depending on the banks and payment system involved.
- Cheque Processing
Cheque processing allows businesses and individuals to make payments using paper checks issued by a bank. Once deposited, the bank verifies and clears the cheque before transferring the funds. This method is still used by some organizations, particularly for business-to-business transactions and charitable donations.
- Cash
Cash remains one of the oldest and most universally accepted forms of payment for everyday purchases. It enables immediate settlement without requiring banks, internet access, or payment devices. Despite the rise of digital payments, cash continues to play an important role in many economies and industries.
- ACH Payments
Automated Clearing House (ACH) payments enable electronic bank-to-bank transfers and are widely used for payroll, invoices, recurring billing, and business payments. ACH transactions typically cost less than card payments but may require longer settlement times. Many businesses use ACH payments for recurring billing because they offer lower processing costs than credit card transactions.
Essential Features of Modern Payment Solutions
Modern payment solutions combine security, convenience, and automation to deliver faster, safer, and more efficient transactions. Here are the key features businesses should look for:
- Multiple Payment Methods – Supports credit and debit cards, digital wallets, bank transfers, BNPL, and other payment options to improve customer convenience.
- Fraud Detection – Monitors transactions in real time to identify suspicious activity and reduce fraud and chargebacks.
- AI Analytics – Analyzes payment data to uncover customer trends and generate actionable business insights.
- API Integrations – Connects seamlessly with websites, mobile apps, eCommerce platforms, and business software.
- Mobile Support – Enables secure, mobile-friendly payments across smartphones and tablets.
- Omnichannel Payments – Delivers a consistent payment experience across online, mobile, and in-store channels.
- PCI DSS Compliance – Protects cardholder data by meeting industry security and compliance standards.
- Tokenization – Replaces sensitive payment information with secure tokens to minimize data exposure.
- Subscription Billing – Automates recurring payments, renewals, and invoicing for subscription-based businesses.
- Reporting Dashboard – Provides real-time reports on transactions, revenue, refunds, and payment performance.
- Cross-Border Payments – Supports international transactions and multi-currency payment processing for global customers.
- Chargeback Management – Helps businesses monitor disputes, respond to chargebacks, and reduce revenue loss.
- Payment Routing – Directs transactions through the most efficient payment path to improve approval rates and reduce processing costs.
Traditional vs FinTech: Which Is Better for Your Business?
Traditional and FinTech payments each serve an important role in today’s payment ecosystem. Traditional payment systems provide trusted banking infrastructure, regulatory oversight, and broad acceptance. FinTech platforms introduce faster payments, automation, flexible integrations, and modern customer experiences.
Rather than choosing one over the other, many businesses benefit from combining both approaches. A hybrid payment strategy allows businesses to support customer preferences, improve operational efficiency, and adapt to changing payment trends.
The right solution ultimately depends on your industry, customer base, transaction volume, growth objectives, and operational requirements. By evaluating these factors carefully, you can build a payment strategy that supports long-term growth.
If you’re looking for an easy way to accept secure digital payments on your WordPress website, WP EasyPay makes it simple to integrate Square payments without complex coding. With features like secure checkout, digital wallets, and more, WP EasyPay helps businesses deliver a modern payment experience.
Frequently Asked Questions
What is the difference between a payment gateway and a payment processor?
A payment gateway securely captures and encrypts payment information when a customer makes a purchase online or in person. It acts as the bridge between the customer, merchant, and payment network. A payment processor handles the actual transaction by communicating with banks and card networks to authorize, process, and settle the payment. In simple terms, the payment gateway collects payment data, while the payment processor moves the money.
Are digital wallets considered FinTech payments?
Yes. Digital wallets are one of the most common types of FinTech payments. They allow users to store payment information digitally and make secure payments through smartphones, smartwatches, or computers. Popular digital wallets include Apple Pay, Google Pay, Samsung Wallet, and PayPal Wallet. They improve convenience, support contactless payments, and often use tokenization to enhance security.
Which payment method has lower transaction fees?
The cost depends on the payment method, provider, transaction volume, and business model. Bank transfers and ACH payments often have lower fees than credit card transactions because they bypass card network charges. FinTech providers may offer competitive pricing and transparent fee structures, while traditional payment providers may charge setup, monthly, or additional service fees. Businesses should compare total processing costs rather than focusing only on transaction fees.
Are FinTech payments safer than traditional payments?
Both FinTech and traditional payment systems can provide strong security when they follow industry standards and regulatory requirements. Many FinTech providers use advanced technologies such as tokenization, encryption, AI-powered fraud detection, and real-time transaction monitoring to protect payment data. Traditional payment providers rely on established banking security controls and regulatory oversight. The overall level of security depends more on the provider’s security practices than on the payment model itself.
Can small businesses benefit from FinTech payment solutions?
Yes. FinTech payment solutions often help small businesses accept payments quickly without complex setup requirements. Many platforms offer easy integrations, lower upfront costs, digital wallets, recurring billing, automated invoicing, and real-time reporting tools. These features allow small businesses to improve customer experience, streamline operations, and scale their payment infrastructure as they grow.
Can a business use both traditional and FinTech payment providers?
Yes. Many businesses use a combination of both to offer customers more payment options, improve reliability, and reduce the risk of payment disruptions.
Are FinTech payment providers regulated?
Yes. Most FinTech companies must comply with financial regulations, data protection laws, and industry standards such as PCI DSS, although requirements vary by country.
Do FinTech payment providers support recurring billing?
Many FinTech platforms offer built-in tools for recurring payments, subscription billing, automated invoicing, and payment reminders, making them popular with SaaS and subscription-based businesses.
What should businesses consider before switching payment providers?
Businesses should evaluate transaction fees, supported payment methods, integration options, customer support, security certifications, payout times, and scalability before making a switch.
Can traditional banks process online payments?
Yes. Many traditional banks offer online payment processing through merchant accounts and payment gateways, although setup may take longer than with many FinTech providers.